

You shouldn’t judge an investment property by its price or appreciation alone. To see how it performs, compare collected rent with vacancy, operating costs, and debt payments; this reveals your net cash flow and the income your invested cash actually earns. Include taxes, insurance, maintenance, management, repairs, and financing risks, then test how rate changes or weaker occupancy could affect liquidity. Local demand also matters: vacancy trends, tenant profiles, and rent changes help you assess whether income can hold up over time. A closer look clarifies the trade-offs.
Measure Returns Beyond Property Prices
To measure an investment property’s performance, look beyond its change in market value and calculate the income it generates after expenses. Market appreciation can increase your equity, but it doesn’t show whether the property earns an adequate return on the capital you’ve invested.
Compare annual operating costs, including property taxes, insurance, maintenance, and management fees, with the property’s value or purchase price. This analysis helps you assess operating efficiency and compare properties on a consistent basis.
You should also account for your investment horizon and the timing of costs. A property that gains value quickly may still underperform if recurring expenses consume too much of its economic benefit.
Use reliable records and conservative assumptions rather than projected resale prices alone. By separating appreciation from operating performance, you can identify what drives returns and make better-informed decisions about holding, improving, or selling the property.
Calculate Rental Income and Net Cash Flow
Rental income shows what a property earns, while net cash flow reveals what remains after operating expenses and debt payments. Start with scheduled rent, then adjust for vacancy and unpaid balances to estimate collected income. Use actual lease terms and market evidence, not optimistic asking rents.
Strong Tenant screening can reduce missed payments and turnover, while disciplined Lease management helps you track renewals, rent changes, and collections.
Next, subtract recurring operating expenses and scheduled debt payments from collected income. Calculate this monthly and annually, keeping the periods consistent. For example, annualize monthly figures before comparing properties.
Review the result alongside occupancy and rent collection rates: positive cash flow indicates income exceeds outflows, while negative cash flow signals a shortfall. Test realistic rent and vacancy scenarios to see how sensitive your cash position is, and update estimates as leases change.
Count Property Costs and Financing Risks
Positive net cash flow doesn’t guarantee a sound investment; you also need to count costs that can erode returns and assess how financing may amplify losses.
Budget for property taxes, insurance, maintenance, management fees, vacancy, and major repairs, not just routine operating expenses. Include renovation expenses and build a reserve for unexpected work; underestimating either can turn projected returns negative.
Then stress-test your financing. Compare fixed and variable rates, calculate debt-service coverage, and model payment increases if rates reset.
Market volatility can reduce property values while leaving your loan balance unchanged, limiting refinancing or sale options. High leverage magnifies that exposure: a small decline in value can sharply reduce your equity.
Check loan terms, fees, and prepayment penalties, and retain enough liquidity to cover costs during disruptions without relying on optimistic resale assumptions.
Assess Local Rental Demand and Growth
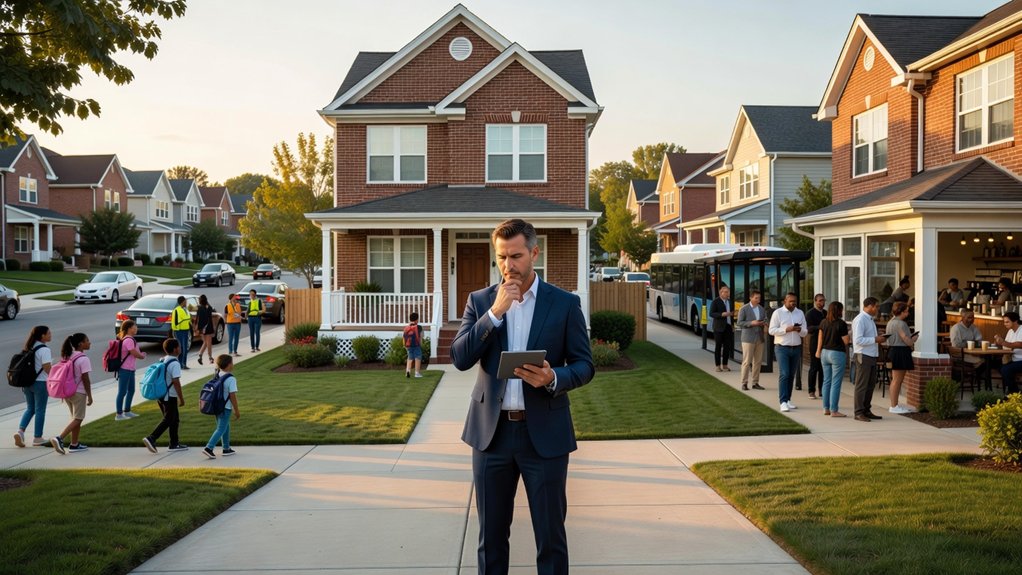
Even when a property’s finances look sound, local demand determines whether it can attract tenants and sustain rent growth. Assess Neighborhood trends by tracking employment, population, new construction, transit access, and planned infrastructure. Compare these indicators across several years; a temporary surge may not support durable demand.
Study tenant demographics to identify who rents nearby, what they can afford, and which features they value. Review household size, age, income, and commuting patterns, then compare those findings with your property’s layout and location.
Local vacancy rates, days on market, lease concessions, and rent changes reveal how quickly units fill and whether landlords can raise rents.
Verify data with property managers, municipal reports, and recent listings. Ask whether demand varies by season or unit type. Use this evidence to judge occupancy prospects and realistic rent growth before committing capital.
Compare Property Investment Returns
To compare property investment returns, calculate net operating income, cash flow, cash-on-cash return, and total return after financing, taxes, and selling costs.
Start with realistic rent, vacancy, maintenance, insurance, management, and capital expenditure assumptions.
Subtract operating expenses from effective rental income to find net operating income; then account for debt service to estimate annual cash flow.
Divide annual pre-tax cash flow by your invested cash to measure cash-on-cash return.
For total return, include principal paydown and market appreciation, but model appreciation conservatively rather than treating it as guaranteed income.
Apply consistent holding periods, financing terms, tax assumptions, and exit costs when comparing properties.
Stress-test rents, vacancy, and interest rates to see how returns change.
Property diversification can reduce exposure to one market, tenant pool, or property type.
Choose investments that fit your risk tolerance and liquidity needs.
Leave a Reply